Access Your Home Equity & Restructure Your Mortgage
Lower Monthly Payments
Explore refinancing options that may help reduce your monthly mortgage payments
Access Home Equity
Access available equity in your home for eligible financial needs and future goals.
Reduce Interest Costs
Review your current interest rate and explore options that may help reduce your overall interest costs.
Expert Guidance
Our mortgage experts can guide you through your refinancing options and help you understand each step of the process
What Is Mortgage Refinancing?
Mortgage refinancing means replacing or restructuring your existing mortgage to obtain a new mortgage amount, terms or lender.
For example, suppose your home is worth $700,000 and you currently owe $400,000 on your mortgage. Your approximate equity is $300,000.
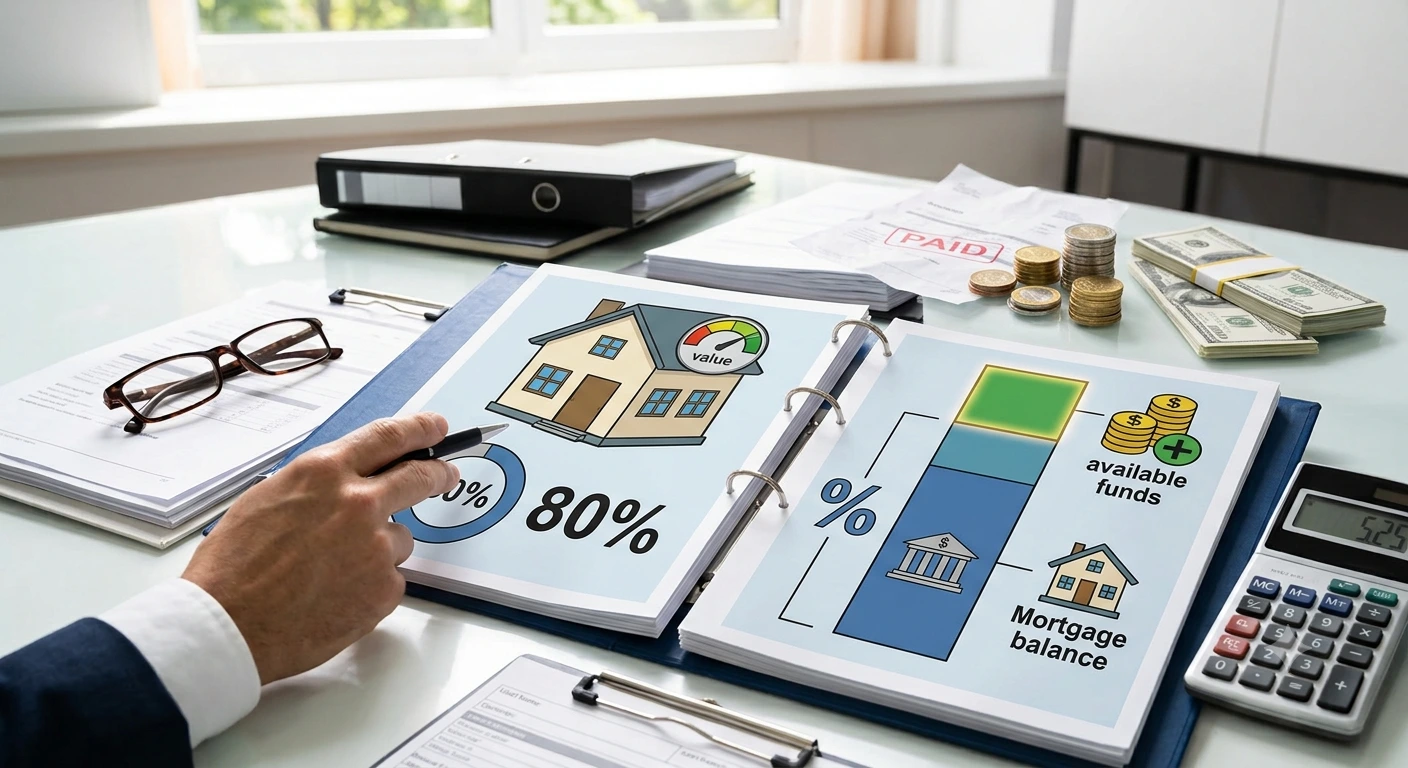
In many conventional refinancing situations, homeowners may be able to borrow up to approximately 80% of the property’s value, subject to lender qualification and other requirements.
At an $700,000 property value: 80% of $700,000 = $560,000If you owe $400,000, there could potentially be up to $160,000 of additional borrowing room before considering closing costs, existing secured debts and lender qualification.
The actual amount available will depend on your complete financial profile and the lender’s guidelines.
Why Do Homeowners Refinance?
Pay for Home Renovations
Refinancing can provide funds for major renovations, additions, repairs or other improvements.
This may be particularly useful when homeowners want to improve their existing property rather than move.
Access Home Equity
Your home equity generally represents the difference between your property’s value and the debts secured against it. Equity can increase as you pay down your mortgage or as your property value rises.
Refinancing may allow you to access some of that equity without selling your home.
Consolidate High-Interest Debt
Refinancing can help consolidate high-interest debts such as credit cards, personal loans, and lines of credit into your mortgage. This may lower your interest rate, but extending the repayment period could increase the total cost.
Change Your Mortgage Strategy
Refinancing may be helpful if your income, debt, renovation plans, payment needs, or investment goals have changed. It can also provide an opportunity to choose a mortgage structure that better suits your current financial situation.
What Do You Need to Qualify for a Refinance?
For federally regulated lenders, the minimum qualifying rate for uninsured mortgages is currently the greater of 5.25% or the mortgage contract rate plus 2%. Refinancing can therefore require you to qualify based on today’s lending requirements—not simply the requirements you met when you originally obtained your mortgage.
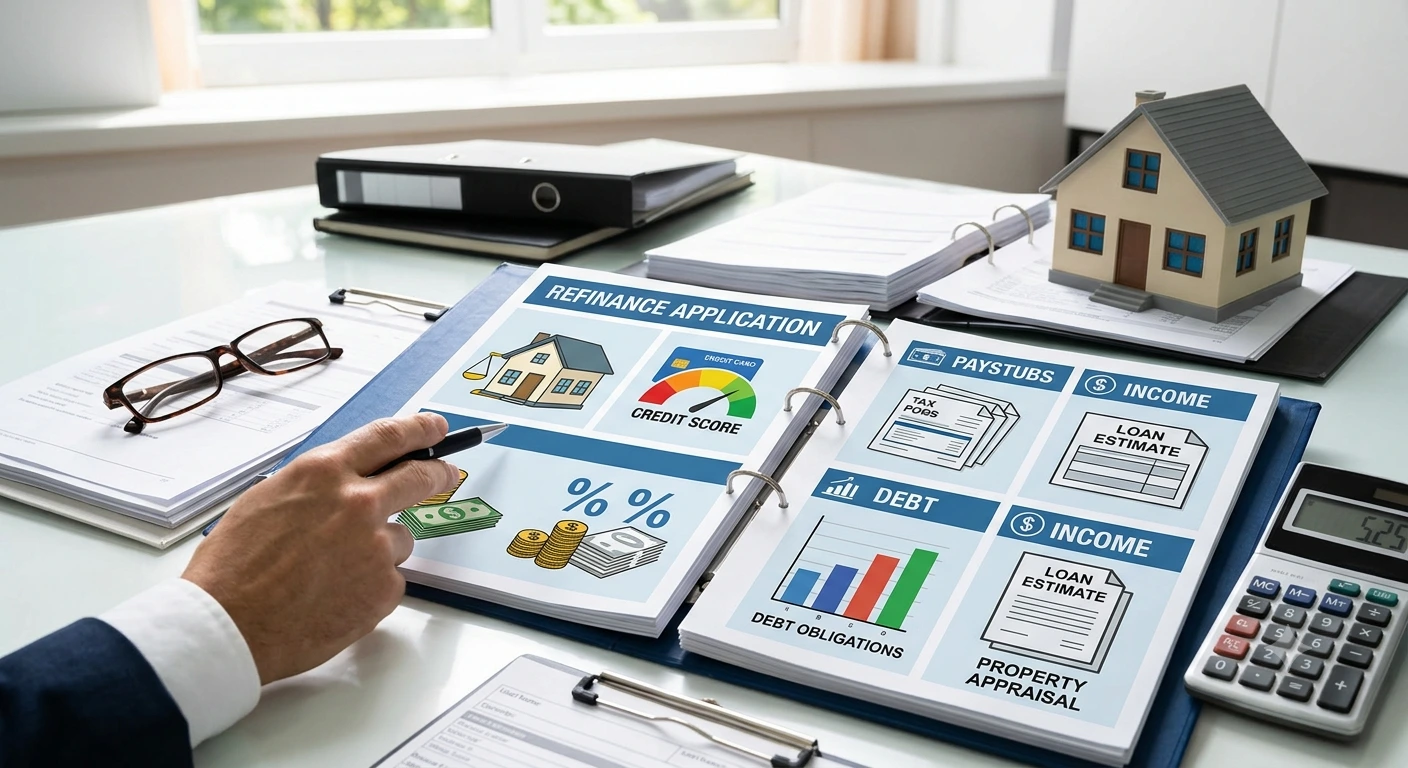
Income: Your employment or business income must support the proposed mortgage payments.
Debt-service ratios: Lenders assess your overall debt obligations compared with your income.
Property value: An appraisal or other property valuation may be required to determine the property's current market value.
Credit: Your credit history and existing debts are important factors in the application.
Mortgage amount: The lender considers the requested loan amount relative to the property's value.
What Does Mortgage Refinancing Cost?
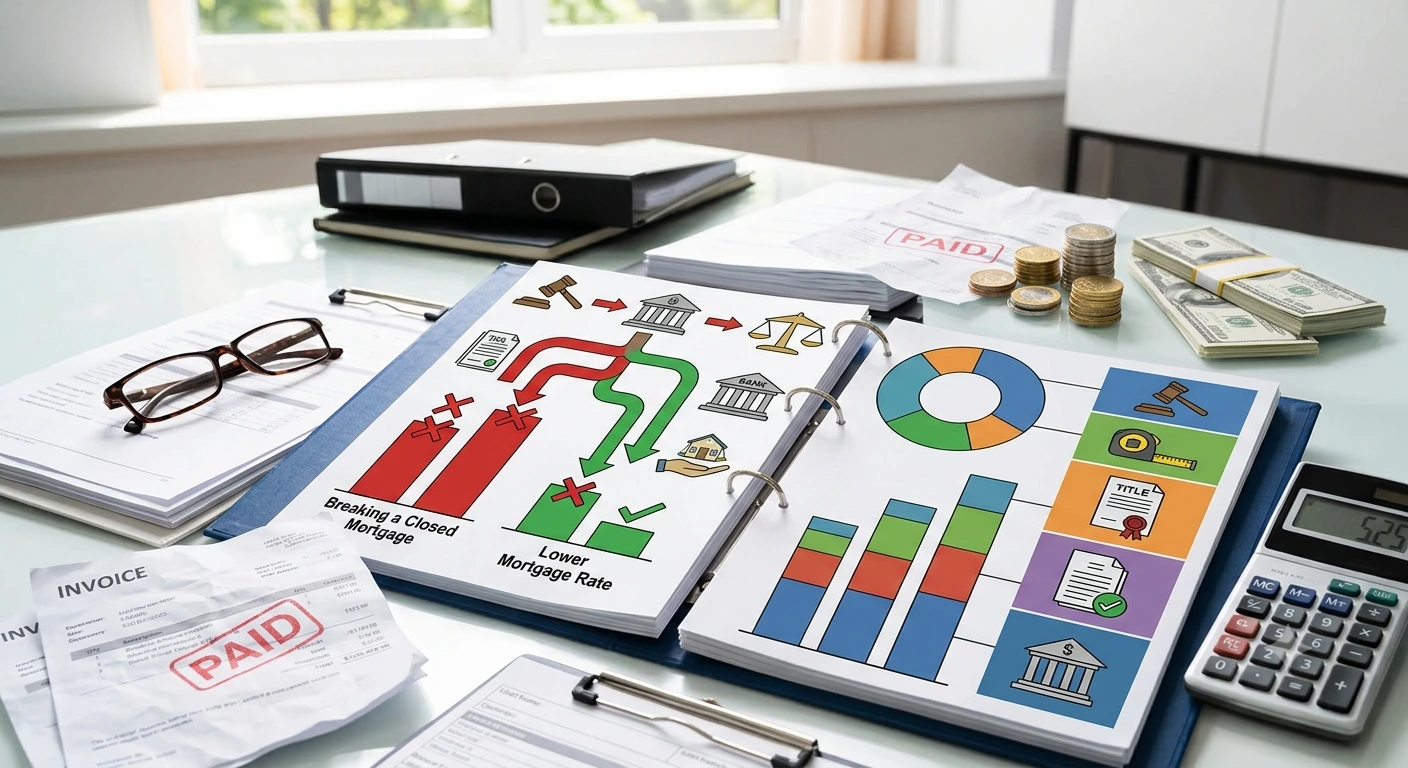
If you break a closed mortgage before the end of its term, your lender may charge a significant prepayment penalty. The penalty can depend on the mortgage terms and may be based on three months’ interest or an interest-rate differential calculation. A lower mortgage rate does not automatically mean refinancing will save you money. The penalty and other costs should be compared with the potential interest savings and benefits.
Mortgage prepayment penalty
Legal fees
Appraisal fee
Title-related costs
Mortgage registration or discharge fees
Lender or administration fees
Other closing costs
Mortgage Refinance vs. Mortgage Renewal
Mortgage renewal generally means renewing your existing mortgage when your current term ends. Mortgage refinancing involves changing the mortgage—often by increasing the amount borrowed, changing the structure, or accessing equity. A refinance is normally treated as a new mortgage application and may involve qualification requirements, appraisal costs, legal fees and other expenses.
How Much Can You Refinance?
For many conventional refinance situations, borrowing is generally limited to approximately 80% of the home’s appraised value, subject to lender requirements and the debts already secured against the property.
For example: Home value: $800,000 Approximate 80% maximum: $640,000 Existing mortgage: $450,000 Potential gross equity available: $190,000
This is only an illustration. Your actual borrowing capacity may be lower depending on your income, credit, debts, property type and lender guidelines.
Should You Refinance Before Your Mortgage Renewal?
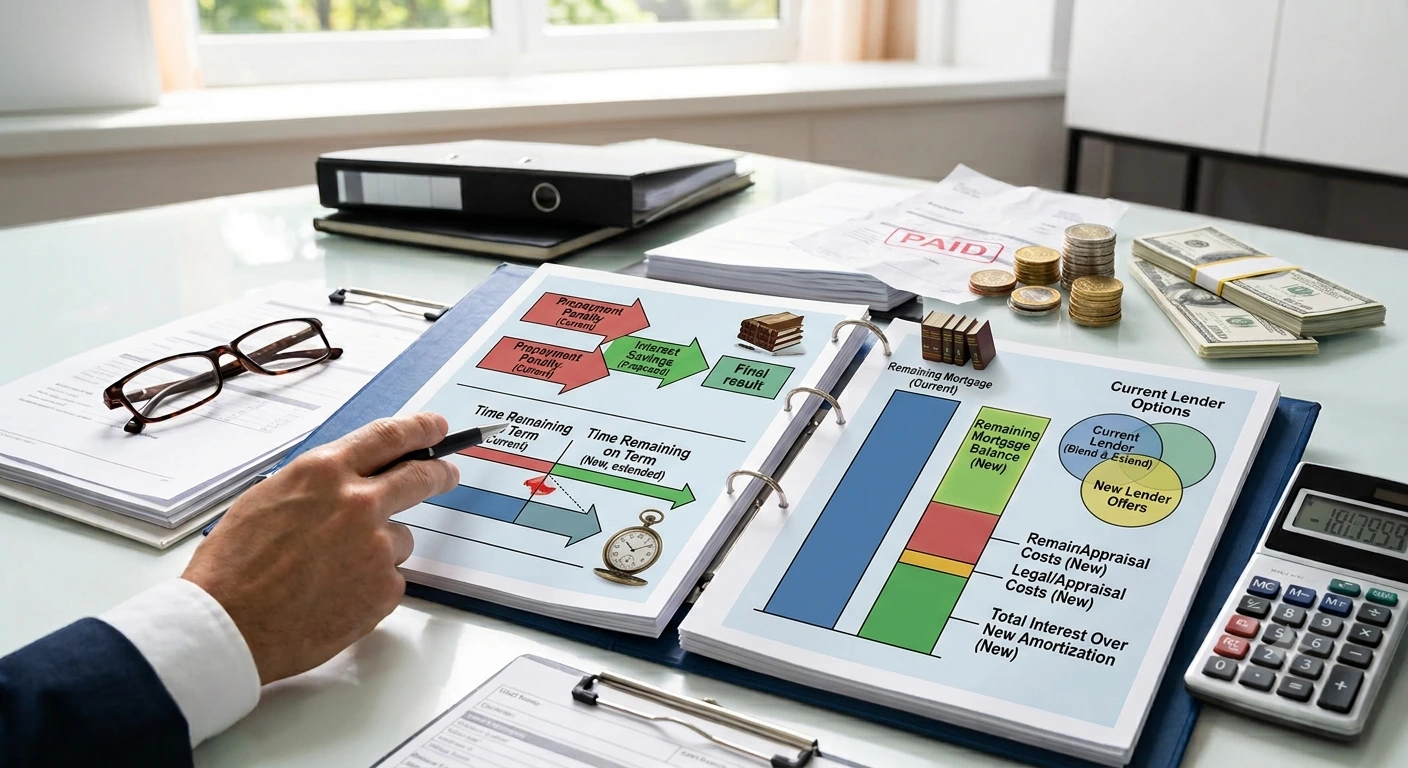
Not necessarily. Sometimes refinancing before renewal makes financial sense. Other times, the prepayment penalty and transaction costs can outweigh the potential benefits.Before making a decision, compare:
Your current mortgage rate
Your proposed new rate
Remaining mortgage balance
Time remaining on your term
Prepayment penalty
Legal and appraisal costs
New payment amount
Total interest over the new amortization
Your current lender may also offer options such as a blend-and-extend arrangement, which can sometimes avoid a traditional break penalty.
How a Mortgage Agent Can Help
Every refinancing situation is different. A mortgage agent can help you review your financial objectives, compare available lender options and determine whether refinancing, a HELOC, second mortgage or another financing strategy may be more appropriate. The goal isn’t simply to find a lower rate—it is to find a financing solution that makes financial sense for your situation.
Ready to Explore Your Refinancing Options?
If you’re an Ontario homeowner considering debt consolidation, renovations, accessing home equity, reducing financial pressure or restructuring your mortgage, let’s review your options before you make a decision.