bad credit mortgage Ontario
Bad Credit Doesn't Always Mean You Can't Get a Mortgage
Have you been turned down by a bank because of your credit history?
Maybe you’ve missed payments, carried high credit-card balances, gone through a consumer proposal, experienced a bankruptcy, or simply haven’t built a strong credit history yet.
A less-than-perfect credit score does not necessarily mean your homeownership plans have to stop
Mortgage lenders look at more than just your credit score. Your income, down payment, debts, employment or business history, property and overall financial situation can all affect your mortgage options.
I help borrowers across Ontario understand their financing options and determine what may be possible based on their individual circumstances.
What Is a Bad Credit Mortgage?
A bad credit mortgage is financing designed for borrowers whose credit history may not meet the requirements
of some traditional lenders.Depending on your circumstances, your options could include financing from:
Bad credit does not automatically mean you need a private mortgage. Some borrowers may still
qualify for traditional financing, while others may need an alternative solution until their credit and financial position improve.
Banks and other prime lenders
Alternative lenders
Mortgage investment leaders
Private lenders
Credit unions
What Can Cause a Mortgage Application to Be Declined?
There are many reasons a lender may decline an application, including:
- Low credit score
- Missed or late payments
- High credit-card balances
- Consumer proposal
- Insufficient down payment
- Bankruptcy
- Collections or unpaid accounts
- Limited credit history
- Unstable or difficult-to-document income
- High debt levels
Your credit score is only one part of the overall application.
Canada’s Financial Consumer Agency recommends checking your credit report before applying for a mortgage and correcting errors that may appear on it.
Can I Get a Mortgage With Bad Credit?
A lender may consider factors such as:
Your Income
Stable, verifiable income can strengthen your application.
Your Down Payment
A larger down payment reduces the amount you need to borrow.
Your Credit History
Lenders may consider your overall credit history, not just your score.
Your Debt
Existing debts can affect your ability to qualify.
The Property
The property's type, location and value may also affect financing options.
Your Options After Credit Challenges
Bad Credit Mortgage Options & Solutions
Even with credit challenges such as bankruptcy, a consumer proposal or a low credit score, mortgage options may still be available. Lenders consider your overall financial situation, including your income, debts, down payment, credit history and the property. Understanding your options can help you choose the right financing strategy and work toward stronger financial stability.

Bad Credit Mortgage After Bankruptcy or Consumer Proposal
Bankruptcy or a consumer proposal does not necessarily prevent mortgage financing. Lenders may consider when it occurred, whether it is completed, your down payment, debts and how well you’ve rebuilt your credit. A stronger financial position can lead to more financing options.
What If My Bank Says No?
A bank declining your mortgage doesn’t mean every lender will. Depending on your situation, options may include another lender, a larger down payment, a co-signer, reducing debt, rebuilding credit or alternative financing
Can I Get a Mortgage With a Low Credit Score?
Potentially. There is no universal minimum credit score for every lender. A lower score may limit your options or affect your mortgage terms, but lenders also consider your overall credit history and financial profile.
How Much Down Payment Do I Need?
There is no single down-payment requirement for bad-credit mortgages. The amount may depend on the purchase price, lender, mortgage type, property and your overall credit and financial profile. Stronger applications may require less down payment, while greater credit challenges may require more.
Will a Bad Credit Mortgage Have a Higher Interest Rate?
It can. Bad-credit borrowers may face higher interest rates or fees due to increased lender risk. Before choosing a mortgage, compare the **total borrowing cost, terms, fees, penalties and exit strategy**.
Can I Improve My Credit and Refinance Later?
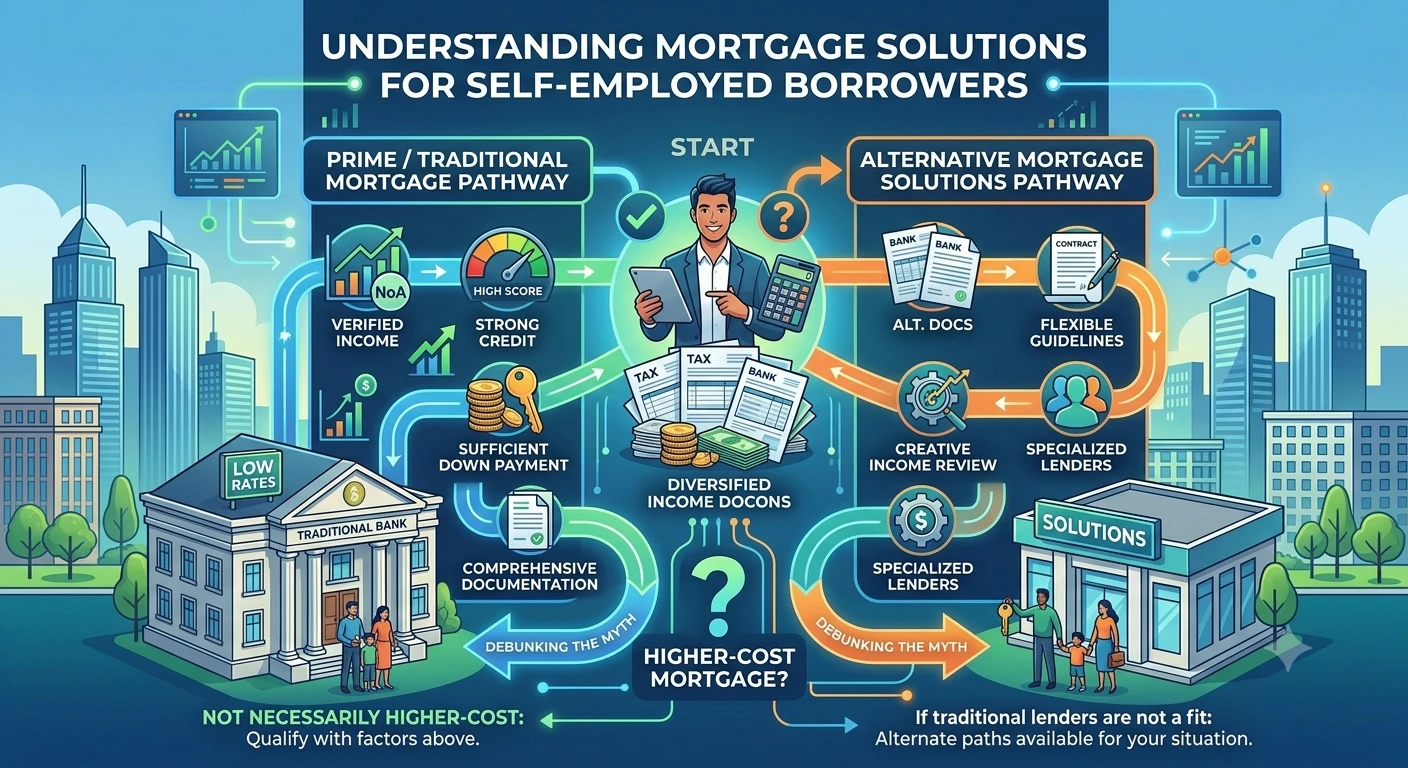
An alternative mortgage can provide temporary financing while you work on improving your financial position. Focus on making payments on time, reducing debt, avoiding unnecessary credit applications, maintaining stable income and building savings. The goal is to strengthen your finances and qualify for better mortgage options later.
Bad Credit Mortgage FAQs
Possibly. Your options depend on your credit history, income, down payment, debts, property and lender requirements.
Potentially. Lenders may consider your current financial position and how you’ve managed credit since the proposal.
Yes. Your personal and corporate financial information may both be considered when assessing your application.
No. Some borrowers with credit challenges may still qualify with traditional or alternative lenders.
A qualified co-signer may strengthen an application, depending on the lender’s requirements and the co-signer’s financial profile.
Not necessarily. The right approach depends on your circumstances. A mortgage review can help determine whether applying now or improving your financial position first makes more sense.
Let's Review Your Mortgage Options
If a bank has said “no,” don’t assume there are no other options.
I’ll review your credit history, income, debts, down payment and property goals to help you understand what mortgage solutions may be available.
Let’s look at your situation and determine your next best step.